
VA Loan Short Sale in Virginia: A Veteran's Guide to Avoiding Foreclosure
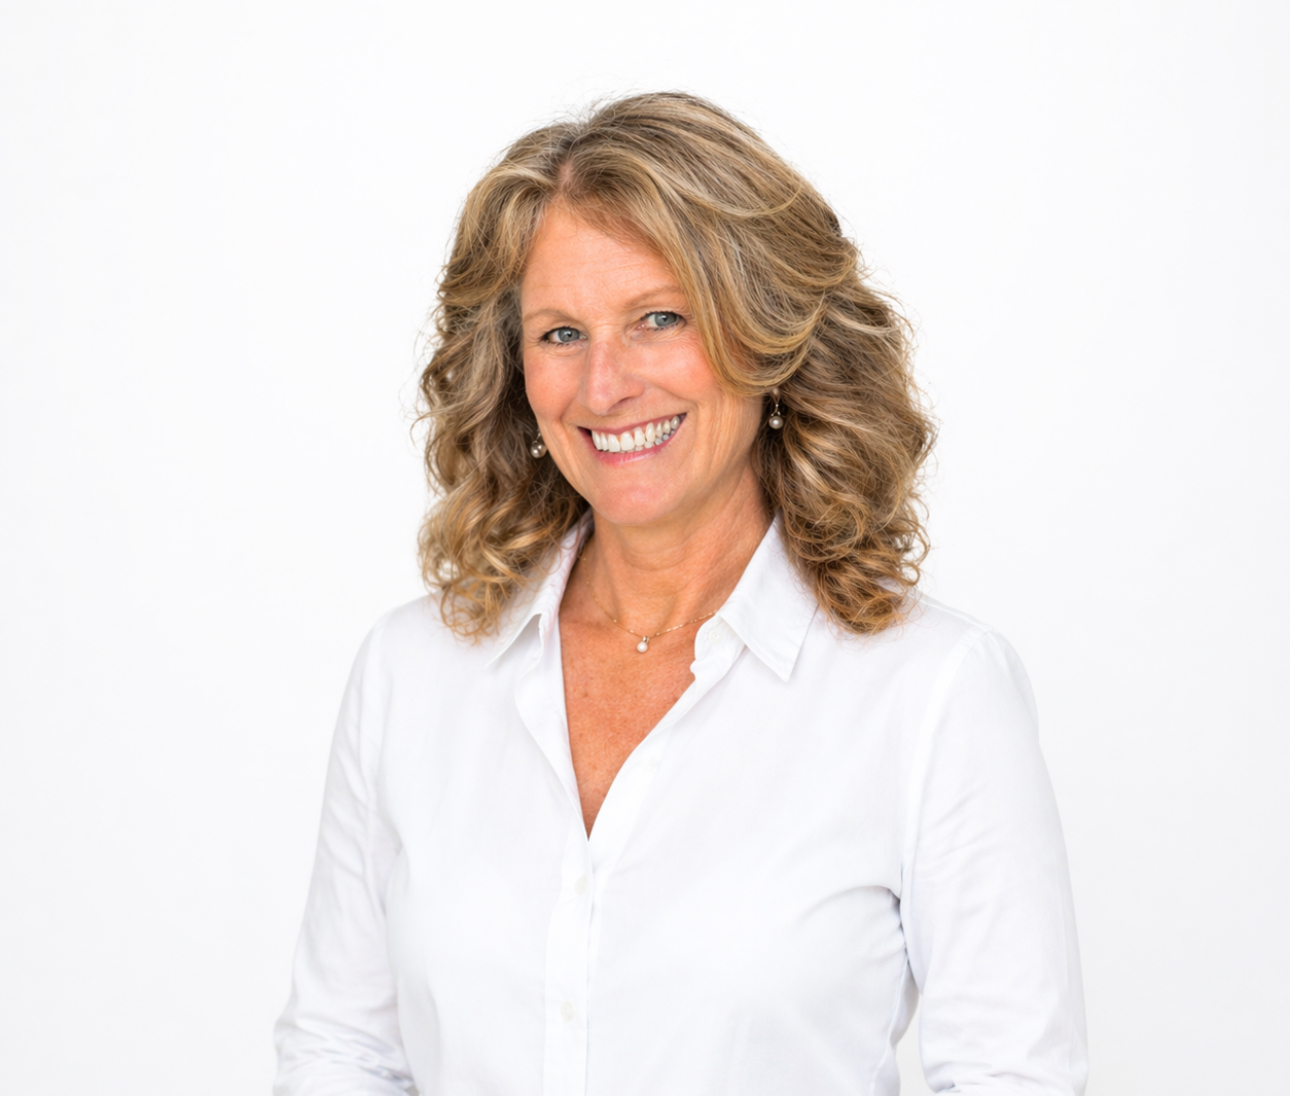
If you are a veteran or active-duty service member with a VA-backed mortgage and the payments no longer fit your budget, a VA short sale, known officially as a VA compromise sale, is one of the most powerful foreclosure prevention tools available in Virginia. It lets you sell your home for less than what you owe with the lender's written approval, and because VA loans are guaranteed, the terms are often notably more favorable than a conventional short sale. Barbara Jennings, REALTOR®, CDPE (Certified Distressed Property Expert), SFR (Short Sales and Foreclosure Resource), and a Member of the National Association of REALTORS®, has helped over 4,000 homeowners complete a short sale and/or stop a foreclosure across Fredericksburg, Stafford, Spotsylvania, King George, and the rest of Northern and Central Virginia.
If your search history holds "short sale realtor near me" or "foreclosure help in Virginia" because you are a military homeowner near Marine Corps Base Quantico, Naval Support Facility Dahlgren, Fort Belvoir, or the Army's training installation in Caroline County, this guide explains how the VA compromise sale works, who qualifies, what happens to your VA entitlement, and how to protect your financial future.
What Is a VA Compromise Sale?
A VA compromise sale is the Department of Veterans Affairs' name for a short sale on a VA-guaranteed mortgage. The home sells for less than the total balance owed, and the VA pays the lender's loss under its loan guaranty, up to the maximum guaranty amount. The veteran is released from the property, the lender is repaid to the extent of the guarantee, and the foreclosure auction is avoided entirely.
The rules that make VA compromise sales different from a conventional short sale are worth knowing before you compare options:
- The home must sell at fair market value, established through a VA-ordered or liquidation appraisal, so the price cannot be artificially low.
- Closing costs must be reasonable and customary, which keeps the sale from being padded with fees that would not survive a normal transaction.
- The seller receives no proceeds from the sale. The VA looks at net return, not what the homeowner walks away with.
- The sale must cost the VA less than a foreclosure would. This comparison drives the approval decision.
Because VA guidelines are strict, a short sale specialist like Barbara Jennings makes the difference between a smooth approval and a file that stalls. Her team knows exactly how the VA expects hardship, value, and net return to be documented before the offer reaches the lender.
Do You Qualify? Hardship and the "Insolvable" Loan
To qualify for a VA compromise sale, you need two things: a genuine financial hardship and a loan that your servicer cannot reasonably cure through a retention option.
Valid hardships include job loss, a reduction in income, major medical bills, the death of the principal wage earner, and, very common in our region, a PCS move or military relocation that forces two housing payments at once. The servicer must also determine that the loan is insolvable, meaning it cannot be brought current through forbearance, a repayment plan, or a loan modification.
A useful detail most homeowners do not know: if your loan is already 60 or more days delinquent and you request a short sale, the servicer generally does not need to re-evaluate your financials before processing it. That does not mean the hardship documentation disappears, but it does mean the process can move faster once you are behind. As a distressed property expert and foreclosure prevention expert, Barbara can tell you quickly whether your situation meets the VA's threshold.
Will You Owe the Difference After a VA Short Sale?
This is the question that keeps veterans up at night, and the answer is genuinely good news for VA loans. Because VA loans are non-recourse, the VA generally does not pursue the borrower for the deficiency after an approved compromise sale. The shortfall between the sale price and the balance owed is absorbed by the VA's guaranty payment to the lender, which is the entire point of the guarantee.
That protection does not exist automatically for every mortgage. In Virginia, when a conventional or FHA loan sells for less than the balance, the lender keeps the legal right to pursue the remaining debt unless the approval letter says otherwise. That is why Barbara and her team, alongside Joe Vance of KJD Resolutions and ATG Title Company, review every VA approval letter word for word. The written confirmation that the sale satisfies the debt in full is the document that protects your future, and it cannot be left to assumptions.
The Virginia Timeline: Why Acting Early Matters
Virginia foreclosures are non-judicial. A home loan here is secured by a deed of trust that gives a trustee the power of sale, so no court filing is required before the auction. The process is governed by Virginia Code §§ 55.1-316 et seq., and it moves on a schedule that can feel surprisingly fast.
- For an owner-occupied home, the trustee must mail written notice of the sale at least 60 days in advance (Virginia Code § 55.1-321).
- The sale must be advertised in a newspaper of general circulation, typically once a week for two successive weeks (Virginia Code § 55.1-322).
- Under the federal mortgage servicing rule, the servicer generally cannot start foreclosure until the loan is more than 120 days delinquent.
Add it up and you have a window of several months from the first missed payment to the courthouse steps. That window is exactly where a short sale lives. As a real estate problem solver, Barbara's first piece of advice is always the same: talk to someone before the auction is scheduled, not after. The earlier you act, the more options you keep.
What Happens to Your VA Entitlement, and Can You Buy Again?
Your VA entitlement is the benefit that guarantees your loan, and a compromise sale changes how much of it remains available. The amount the VA pays the lender for the loss is charged against your remaining entitlement, and that used portion stays tied up until the VA's loss is repaid in full. A short sale does not revoke your Certificate of Eligibility, and it does not touch your other VA benefits.
Many veterans still hold remaining or second-tier entitlement after a compromise sale and can get a new Certificate of Eligibility showing the available balance. The VA itself sets no mandatory waiting period, but most lenders want to see about two years pass after a short sale before they will write a new VA loan, so plan for a period of credit rebuilding followed by a fresh start. Our guide on buying again after a short sale walks through the waiting periods for every loan program, VA included.
SCRA Protections for Active-Duty Service Members
If you are on active duty, the Servicemembers Civil Relief Act gives you protections that apply before and during any of this. The SCRA caps interest on pre-service debts at 6 percent, protects you from default judgments, and lets a court stay foreclosure proceedings while you are serving. PCS orders count as a genuine hardship for a VA compromise sale, which makes the short sale path work hand in hand with your military lifestyle.
These protections exist to buy you time, not to make the stress disappear. Pairing SCRA relief with a Virginia short sale lets you resolve the property on your terms instead of the auctioneer's, which is why service members stationed around Quantico, Dahlgren, Belvoir, and the installations from Fredericksburg to Arlington and Alexandria make Stafford foreclosure help and Spotsylvania short sale services part of their PCS planning. Barbara Jennings serves every one of those counties and understands how orders, deployments, and housing allowances shape the decision.
Why Work with a VA Short Sale Specialist in Fredericksburg?
VA compromise sales are a specialty within a specialty. The paperwork, the appraisal rules, the net-return math, and the entitlement reporting all follow VA-specific guidelines that a generalist agent has no reason to know. That is where Barbara Jennings and her team come in.
Barbara's team partner is Joe Vance with KJD Resolutions, an experienced negotiator who handles the lender-facing side of the short sale, and ATG Title Company, an attorney-backed title company that handles closing transactions for short sales. Using the same title company that negotiates the short sale and continues to provide all of the paperwork to the homeowner in financial distress makes for a much smoother, easier transaction. The title company already understands the full history of the case, has all the lender documentation, and can keep the closing on track without delays or miscommunication. For a service member juggling a PCS, a family, and a mortgage, that continuity is worth more than any discount on closing services.
A Note for Buyers of a VA Short Sale
While Virginia law says buyers CAN choose whatever title company they would like to represent them, in short sale situations it is strongly recommended that the buyer use the title company the listing agent has already been negotiating with. Switching title companies mid-transaction can cause significant delays, require re-submission of documents already provided to the lender, and potentially derail the entire short sale approval. If you are buying a VA short sale in the Fredericksburg area, ask your agent about this before you select a settlement provider.
As a lender negotiation specialist offering financial hardship solutions across Northern and Central Virginia, Barbara approaches every VA short sale the same way: protect the veteran, protect the entitlement, and close the file with a clean written release.
Facing a VA Loan You Cannot Afford? You Have Options
If your VA mortgage payments have become unsustainable, or you are searching for a short sale realtor near me who actually understands military housing, contact Barbara Jennings for a free confidential consultation. There is no cost, no obligation, and complete discretion.
Barbara and her team, alongside Joe Vance of KJD Resolutions and ATG Title Company, have helped over 4,000 homeowners complete a short sale and/or stop a foreclosure. Whether you need a Fredericksburg VA short sale specialist or you are comparing the best short sale agent in Fredericksburg by credentials, the first step is a private conversation about your specific situation.
REALTOR® · 0225179074 · VA · eXp Realty
Why Veterans and Military Families Trust Barbara Jennings
VA short sales demand a rare combination: knowledge of VA guidelines, relentless lender negotiation, and empathy for families serving our country. Barbara Jennings brings all three, backed by over 20 years in real estate and thousands of resolutions for homeowners facing the hardest call of their lives.
Credentials That Matter in a VA Short Sale
- CDPE: Certified Distressed Property Expert, with specialized training in helping homeowners avoid foreclosure through short sales and strategic alternatives.
- SFR®: Short Sales and Foreclosure Resource, with advanced knowledge of short sale transactions, lender negotiation, and distressed property procedures.
- REALTOR®: Member of the National Association of REALTORS®, bound to the highest ethical standards in real estate.
- AI-Certified: advanced artificial intelligence training in real estate marketing, pricing strategy, and client service, giving military families a modern, data-driven advantage.
- VA License #0225179074 · Brokerage: eXp Realty
Barbara works alongside Joe Vance of KJD Resolutions, with closings handled by ATG Title Company. Because the same title company that negotiates the short sale also handles the closing, the entire process runs smoother: ATG already understands the full history of the case, has all the lender documentation in-house, and can keep the closing on track without delays or miscommunication.
As a trusted short sale resource for veterans across the region, Barbara Jennings is the Fredericksburg VA short sale advisor that military families from Stafford to Spotsylvania, King George to Prince William, and Fairfax to Alexandria turn to for foreclosure help in Virginia. If you are ready to make your next move, one confidential conversation is all it takes to see your options clearly.
Frequently Asked Questions About VA Short Sales in Virginia
What is the difference between a VA compromise sale and a regular short sale?
A VA compromise sale IS a short sale, but it runs through the VA's specific program for VA-guaranteed loans. The VA pays the lender's loss under the guaranty, the home must appraise at fair market value, the sale must cost the VA less than foreclosure, and the veteran generally is not pursued for the remaining balance. A conventional short sale has none of those guaranteed protections.
Will the VA come after me for the money owed after a short sale?
In most cases, no. VA loans are non-recourse, so after an approved compromise sale the VA generally does not pursue the veteran for the deficiency. The shortfall is covered by the VA's guaranty payment to the lender. Barbara's team still reviews every approval letter to make sure the written terms confirm the debt is satisfied in full.
Do I need to be behind on my VA loan payments to do a short sale?
No, but you must be able to document a real financial hardship, such as a PCS move, job loss, reduced income, or medical bills, and your servicer must find the loan insolvable. A useful detail: if the loan is already 60 or more days delinquent and you request a short sale, the servicer generally does not need to re-evaluate your financials, which can speed up the process.
What happens to my VA loan entitlement after a compromise sale?
The amount the VA pays the lender for the loss is charged against your remaining entitlement, and restoring it requires repaying the VA in full. Many veterans still have second-tier entitlement available and can obtain a new Certificate of Eligibility showing the balance. A short sale does not revoke your COE or affect your other VA benefits.
How long after a VA short sale can I get a VA loan again?
The VA itself sets no mandatory waiting period, but most lenders want about two years after a short sale before they will approve a new VA loan. That timeline depends on your credit recovery and income. Barbara can walk you through the realistic path to buying again after the short sale closes.
I am on active duty. Do SCRA protections apply during a short sale?
Yes. The Servicemembers Civil Relief Act caps interest on pre-service debts at 6 percent, protects you from default judgments, and can stay foreclosure proceedings while you serve. PCS orders count as a genuine hardship for a VA compromise sale, so SCRA protections and a Virginia short sale can work together to resolve the property on your terms.
A VA short sale is a serious decision, but it is also a proven path used by tens of thousands of veterans every year. Read the complete short sale guide or reach out to Barbara Jennings for a free confidential consultation about your specific situation.
Disclaimer: This article is for informational purposes only and does not constitute legal, financial, tax, or housing counseling advice. VA loan guidelines, servicer requirements, and entitlement rules change over time, and outcomes depend on individual circumstances. Consult with the VA, your loan servicer, a qualified attorney, and a licensed real estate professional to discuss your specific situation. Information deemed reliable but not guaranteed.